
Pay Per Mile Car Insurance, Explained
Have stellar driving habits and spend less time behind the wheel than the average driver? Pay per mile car insurance could be a great fit.
Have stellar driving habits and spend less time behind the wheel than the average driver? Pay per mile car insurance could be a great fit.
Pay per mile car insurance has two parts: a base price that stays the same, and a few cents for each mile you drive. The fewer miles you rack up, the lower your bill.
It’s also called usage-based or pay as you go insurance. We’ll stick with pay per mile here.
 TL;DR
Pay per mile is a type of car insurance that mostly prices your policy by the miles you drive. Each month, you pay your miles multiplied by your per-mile price, plus your base price.
That usually means low-mileage drivers end up with lower rates, saving as much as 40% a year.
The coverage is largely the same. The big difference is how your premium is calculated. Your price changes every month based on how many miles you drive.
Mileage matters on traditional policies too. You may get a low-mileage discount if you drive less than the average American, who drives around 13,476 miles a year (about 1,100 miles a month).
You pay a monthly base price that doesn’t change. On top of that, you pay a per-mile price based on how much you drove that month. The per-mile price looks tiny, just cents, but it adds up.
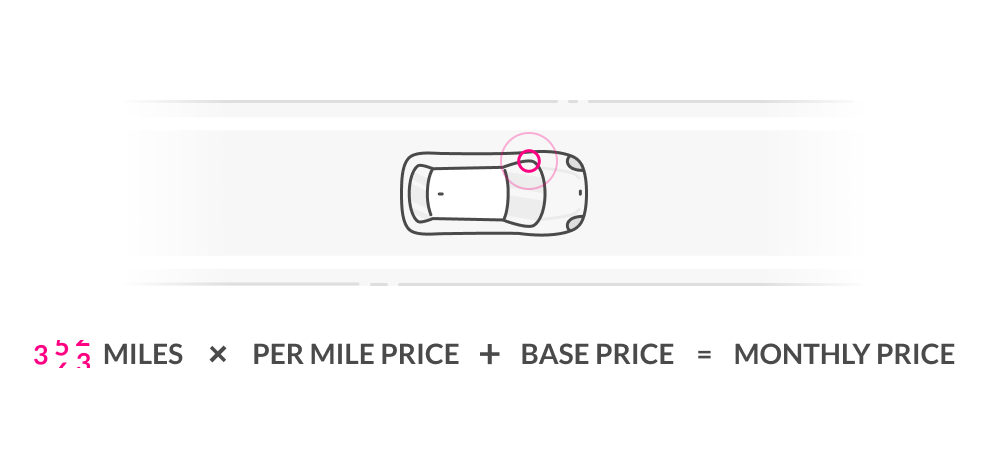
Here’s the formula in action. Say your policy has a $29 monthly base rate and a 6¢ per-mile price.
That’s why pay per mile appeals to low-mileage drivers.
These numbers are hypothetical. Your own price will vary with your state, your insurer, your driving history and habits, your car’s make and model year, and the coverages on your policy.
When you shop for quotes, insurers usually ask you to estimate your annual mileage. They may ask you to verify it with an odometer reading later.
To estimate your annual mileage, check the mileage on your odometer and divide it by your car’s age. Don’t know the age? The model year is on the driver’s door jamb.
Once you’re on a pay per mile program, your insurer needs an accurate monthly reading. Mileage is usually tracked with a simple mobile app or a plug-in device in your car.
Yes. Pay per mile policies include the same standard coverages and add-ons as traditional policies, like liability, comprehensive, and collision. (Confused about the differences? We clear it up here.)
Customize your coverages to fit your needs. Just know that your choices affect the monthly base rate in your premium.
Insurers weigh a lot of factors beyond mileage, like your driving behavior and your driving record.
Because the app or device is already along for the ride, it can usually sense more than miles. It can generally tell if you speed or brake harshly.
It also registers your good habits, like driving in the daytime and sticking to well-maintained roads. A steady record of safe driving can help lower your price.
Pay per mile is built to help low-mileage drivers save money. One road trip shouldn’t wreck that. These programs generally have buffers for the occasional long drive.
Some programs set a daily limit, so you aren’t charged after a certain number of miles in a single day. The limit varies by insurer and state, so check before you hit the open road.
Does your car stay in park most of the time? Then a pay per mile program could be a cheaper option than a traditional policy.
The flip side: if you drive a lot every month, pay per mile probably isn’t for you. These programs are made for low-mileage lifestyles.
Below are six driver profiles where pay per mile tends to shine. Each one uses the same hypothetical rate from above ($29 base plus 6¢ a mile), so you can see how much pay-per-mile insurance costs in real life.
The situation: Your commute is about 15 steps from bed to desk. A typical month includes a weekly grocery run, a few errands, a weekend with friends, and now and then a day at the office. That’s roughly 400 miles, about a third of what the average American drives.
The problem: A traditional policy usually doesn’t change from month to month, even if you add a low-mileage discount. You pay about the same whether you drive 400 miles or 1,200.
The pay per mile fix: This is where low-mileage car insurance earns its keep. At 6¢ a mile, 400 miles costs $24 in mileage charges.
The outcome: Add the $29 base and you’re at about $53 a month. A traditional policy for the same driver could run $100 or more, a savings of around 47%. Want to know your own number? A quote will tell you, since base prices vary by state, car, and driving history.
The situation: You take the train to work, grab a Lyft when it’s pouring, and save the car for weekend trips and the occasional big grocery haul. Some weeks it barely leaves its parking spot. Call it about 300 miles a month.
The problem: A traditional policy prices you like any other car owner, even though you skip the gridlock and the parking headaches. Rides in someone else’s car don’t add a single mile to yours, but they don’t lower a flat premium either.
The pay per mile fix: Usage-based insurance savings come from the gap between how much you drive and how much the average driver does. At 300 miles, mileage charges come to $18.
The outcome: With the $29 base, you’d pay about $47 a month, compared with $100 or more on a traditional policy. That’s more than half off. In months when you ride more and drive less, your bill slides closer to the base price. A phone app does the tracking, so there’s nothing to log by hand.
The situation: Your days are lectures, the library, and your dorm. The car mostly sits in a campus lot, then comes out for the occasional trip home and a stock-up run. That’s about 250 miles on a typical month.
The problem: A traditional policy assumes you drive like the average American. Your car spends most of the semester parked, so you could be paying for miles you’ll never drive.
The pay per mile fix: This is pay-as-you-go car insurance at its simplest. 250 miles at 6¢ comes to $15 in mileage charges.
The outcome: Add the $29 base and you’re at about $44 a month, versus $100 or more on a traditional policy. That’s roughly 56% less. Heading home for winter break? A 600-mile month would run about $65, still well under that traditional price. Some programs also cap what you’re charged on a single day, which varies by insurer and state, so ask before a long drive.
The situation: The long commute is gone, and you probably don’t miss it. Your month now looks like a farmers market run, doctor’s appointments, time with the grandkids, and a weekly round of golf. All told, that’s about 500 miles.
The problem: Your routine changed, but your premium might not have. A flat-rate policy can keep charging you as if you still drive to the office five days a week.
The pay per mile fix: Telematics insurance measures what you really drive. 500 miles at 6¢ comes to $30 in mileage charges.
The outcome: With the $29 base, that’s about $59 a month, compared with $100 or more on a traditional policy. That’s around 41% less. Good habits help too. The same app that counts your miles can register daytime driving and smooth braking, which can work in your favor.
The situation: Maybe the convertible goes into the garage from November through March. Or maybe the car only comes out on weekends. In the summer, you drive about 600 miles a month. In the winter, it’s zero.
The problem: A traditional policy charges the same amount in January, when the car doesn’t move, as in July, when it’s out every weekend.
The pay per mile fix: By the formula, a month with no driving costs just your base price. A 600-mile summer month costs $36 in mileage charges plus the $29 base. If you have a busy stretch, some programs cap daily charges, so one huge driving day won’t be billed in full. The limit varies by insurer and state.
The outcome: Say five parked months at $29 and seven driving months at $65. That averages out to about $50 a month, or roughly half of a $100-plus traditional policy.
The situation: You walk, bike, or take the subway almost everywhere. The car is for weekend getaways, hauling furniture, and the “we need to get to the airport at 5 a.m.” moments. You drive fewer than 500 miles a month, often closer to 150.
The problem: A flat-rate policy doesn’t know your car spends most days parked on the street. You carry the cost of a full-time driver without the full-time driving.
The pay per mile fix: With pay-per-mile pricing, your bill follows your actual usage. 150 miles at 6¢ is $9 in mileage charges.
The outcome: Add the $29 base and you’d pay about $38 a month. Even at 500 miles, you’d pay about $59. A traditional policy could run $100 or more. Your city address can affect your base price, so a quote gives you the real number.
The prices below use the hypothetical rate of $29 base plus 6¢ per mile. Real prices vary by state, car, and driving history.
| Driver type | Estimated monthly miles | Estimated pay-per-mile premium |
|---|---|---|
| Average American driver (benchmark) | About 1,200 | $101 |
| Remote worker | About 400 | $53 |
| Public transit and rideshare rider | About 300 | $47 |
| College student on or near campus | About 250 | $44 |
| Retiree | About 500 | $59 |
| Seasonal or part-time driver | 0 to 600 (varies by season) | $29 to $65 |
| Urban apartment dweller | 150 to 500 | $38 to $59 |
The short answer: Lemonade Autonomous Car insurance is a pay per mile policy for Tesla owners. It charges you less for miles driven with self-driving on: 50% off with FSD and 30% off with FSD Lite.
It costs less because FSD miles are safer than manual driving, so we pass the savings to you.
FSD stands for Full Self-Driving. It’s a driver-assist mode on newer Teslas with Hardware 4, which is Tesla’s latest onboard computer. Despite the name, it isn’t fully autonomous. You still supervise the drive.
FSD Lite is the version made for older Teslas, specifically 2019 and newer Model 3 and Model Y cars with Hardware 3. You supervise here too, and the discount is a bit smaller.
With your permission, Lemonade connects directly to your Tesla. The connection shows which miles were driven in FSD and which were driven manually. There’s no guesswork and nothing to log by hand.
Setup takes three steps:
You can follow your FSD miles and savings in the Lemonade app.
The FSD discount applies to your per-mile price. Using the same sample rate from earlier ($29 base plus 6¢ a mile), here’s what it could look like:
These are hypothetical numbers. Your price depends on your state, your Tesla, your driving history, and your coverages.
Which discount you get depends on your Tesla. Newer Teslas with HW4 hardware running FSD v14.2 or later get 50% off FSD miles. Older Teslas with HW3 hardware running FSD v14 Lite get 30% off FSD Lite miles.
Not sure which one you have? Check your Tesla’s hardware and software version, or connect it when you get a quote and Lemonade will show you what you qualify for.
No. Lemonade supports occasional FSD use. It also covers households with a mix of Teslas and non-FSD cars from other manufacturers, all under one policy. You only get the discount on the miles you actually drive with FSD on.
Lemonade says it might. The company expects further reductions as Tesla releases FSD software updates, which are anticipated to make cars even safer over time. That’s an expectation, not a guarantee, so your own price can change.
Lemonade Autonomous Car insurance is available for Tesla drivers in select states, with more coming. A quote will tell you right away if it’s available where you live.
Drive a Tesla with FSD? See how much you could save on every FSD mile.
If your car spends more time parked than moving, you’re probably paying for miles you don’t drive.
Pay per mile fixes that. You pay a base price, plus a few cents for each mile. In our sample math, the drivers in this guide pay between $29 and $65 a month. A traditional policy could run $100 or more.
Here’s a quick way to check:
Your real price depends on your state, your car, and how you drive, so sample numbers only go so far. A quote gets you your own number.
Ready to see your price? Get a quote and find out what you’d pay for the miles you actually drive.
Pay-per-mile insurance can be very cost-effective for low-mileage drivers. If you drive significantly less than the average American, you might save a considerable amount on your premiums.
There’s generally no minimum mileage requirement for pay-per-mile insurance, meaning you can save money even if you drive just a few miles a month. The less you drive, the more you save, which is ideal for people whose cars spend most of their time parked.
Your base rate continues to cover your vehicle even during months when you don’t drive, which ensures that your car is protected from non-driving-related incidents like theft or weather damage.
If your car is frequently used by multiple drivers, inform your insurer to ensure coverage accuracy. Pay-per-mile policies typically account for the vehicle’s total mileage, regardless of the driver.
While both reward low-mileage drivers with lower premiums, pay-per-mile insurances more dynamically adjust your monthly premium based on actual miles driven, rather than applying a standard discount for reporting low mileage per policy term.
No. Tesla Insurance is exclusive to Tesla vehicles. It uses real-time driving data from Tesla’s own systems, which aren’t available in other vehicles. If you drive a different make, you’ll need to shop standard insurers and compare quotes based on your driving record and vehicle. Read the full thread on Reddit
New Teslas are expensive to repair, have limited certified repair shops, and use costly parts. A minor accident can result in a total loss if the battery is damaged. Their strong safety ratings help offset some costs, but repair expenses tend to dominate pricing. Tesla Insurance may be worth comparing for Tesla-specific coverage. Read the full thread on Reddit
Teslas cost more to insure due to specialized parts, limited repair networks, and high replacement costs. A Model Y can cost significantly more to insure than a comparable gas SUV. Advanced safety features help, but repair costs tend to dominate pricing. Shopping multiple insurers, including Tesla Insurance, is worthwhile to find the most competitive rate. Read the full thread on Reddit
Salvage title vehicles can be harder to insure and may cost more even for liability-only coverage due to safety concerns and higher claim likelihood. Some insurers won’t cover salvage vehicles at all. When coverage is available, rates are often 10-20% higher than clean title vehicles. Availability and pricing vary significantly by insurer. Read the full thread on Reddit
A few quick words, because we <3 our lawyers: This post is general in nature, and any statement in it doesn’t alter the terms, conditions, exclusions, or limitations of the policies issued, which differ according to your state of residence. You’re encouraged to discuss your specific circumstances with your own professional advisors. The purpose of this post is merely to provide you with info and insights you can use to make such discussions more productive! Naturally, all comments by, or references to, third parties represent their own views, and Lemonade assumes no responsibility for them. Coverage may not be available in all states. Please note that statements about coverages, policy management, claims processes, Giveback, and customer support apply to policies underwritten by Lemonade Insurance Company or Metromile Insurance Company, a Lemonade company, sold by Lemonade Insurance Agency, LLC. The statements do not apply to policies underwritten by other carriers.
Please note: Lemonade articles and other editorial content are meant for educational purposes only, and should not be relied upon instead of professional legal, insurance or financial advice. The content of these educational articles does not alter the terms, conditions, exclusions, or limitations of policies issued by Lemonade, which differ according to your state of residence. While we regularly review previously published content to ensure it is accurate and up-to-date, there may be instances in which legal conditions or policy details have changed since publication. Any hypothetical examples used in Lemonade editorial content are purely expositional. Hypothetical examples do not alter or bind Lemonade to any application of your insurance policy to the particular facts and circumstances of any actual claim.